Why Most Crypto Projects Collapse 6 to 8 Months After TGE — And the Red Flags That Predict It
Most token projects that fail post-TGE made their fatal decisions six months before launch. Here are the nine structural red flags that predict a post-launch collapse, and what healthy alternatives look like.

Ashish Homkar
Founder & CEO
- Published
- Reading time
- 8 min read
The pattern is consistent. A project generates real excitement during its raise. Community grows. Token launches. Price pumps. And then, six to eight months after TGE, something breaks. Price drops 50% or more in a single week. The founder goes quiet. Liquidity disappears.
What looks like a sudden collapse from the outside is almost always the predictable result of decisions made months before the token ever launched. This post documents the nine most common structural failures that predict post-TGE collapse, drawn from real project observations and client advisory work at Blockphrase.
The 9 Red Flags That Predict Post-TGE Collapse
01 — Raising capital before the product exists
Fundraising on the basis of a token before any working product is live means the entire valuation rests on narrative. When the product is delayed, there is no utility to sustain token demand. The raise happened on vibes, and vibes do not hold price.
02 — Vesting schedules designed for insider exits
Vesting terms that allow large, rapid unlocks are a clear signal of a project designed to extract rather than build.
Red flag pattern: 6-month cliff, 25% unlocked on Month 7, remainder vested over just 5 months.
Healthy structure: Post-cliff vest extended over 24 to 36 months with linear or milestone-linked unlocks.
03 — Absent or performative marketing strategy
"Our product speaks for itself" is not a go-to-market strategy. Projects that underspend on structured marketing arrive at listing with insufficient liquidity demand and no organised buyer base. Post-TGE price action depends entirely on organic interest, which is never enough.
04 — No real liquidity or market-making strategy
A $5,000 margin for market-making is not a liquidity strategy. Tokens with insufficient market-making depth experience massive bid-ask spreads, price manipulation by small wallets, and immediate collapse on any meaningful sell order.
05 — Overfunding leading to operational drift
Raising significantly more than the project requires reduces the urgency that drives execution. Founder motivation weakens when financial pressure is removed. Investor influence grows disproportionate to their strategic value, leading to governance conflicts.
06 — Treating regulatory compliance as optional
Relocating to a jurisdiction perceived as crypto-friendly does not substitute for actual regulatory compliance. MiCA, VARA, and equivalent frameworks have specific requirements around token classification, whitepaper disclosures, and issuer obligations that apply regardless of where the founder is based.
07 — Smart contracts that do not match the vesting schedule
A project publishes a vesting schedule in its whitepaper but the deployed smart contracts contain different unlock parameters. Insiders can then exit on the on-chain schedule rather than the disclosed one. Every vesting schedule must be independently audited before launch.
08 — Poorly structured OTC deals linked to VWAP
Over-the-counter token deals that tie settlement price to VWAP create an incentive for the counterparty to manipulate trading volume and price to optimise their settlement terms. Retail token holders bear the cost of this without ever knowing the deal exists.
09 — No coherent ecosystem revenue model
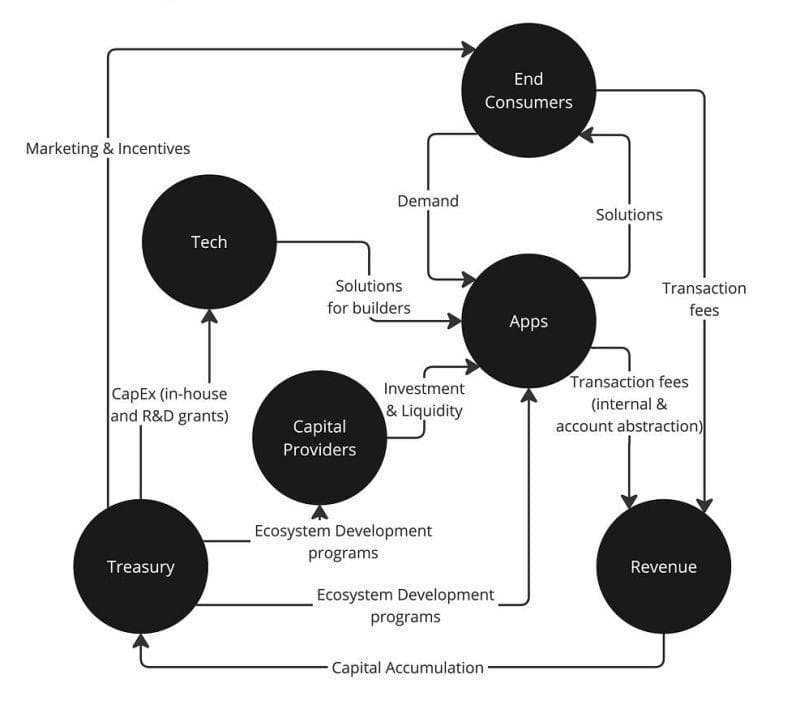
A healthy token ecosystem generates revenue that flows back through the system: from end consumers through applications, through transaction fees, into treasury and back into ecosystem development. Without this circuit, the only value driver is new buyer entry. That is the definition of an unsustainable structure.
What a Healthy Vesting Structure Looks Like
| Period | Red flag | Defensible structure |
|---|---|---|
| Cliff | 6 months | 12 months minimum |
| First unlock | 25% unlocked immediately on Month 7 | Linear, small increments begin post-cliff |
| Full vest | Remainder over just 5 months | 24 to 36 months, milestone or time linked |
| Verification | Whitepaper only | On-chain, independently audited |
Every vesting schedule disclosed in investor materials must be independently verified against the deployed smart contract code before launch. If they do not match, the disclosed schedule is meaningless.
The Decisions That Matter Are Made Before TGE
Post-TGE collapses feel sudden. They are not. Every one of the nine failure patterns above is a decision — or a non-decision — made during the design and preparation phase. The market does not create these failures. It exposes them.
If you are evaluating a token project for investment — or reviewing your own project's readiness — run it against these nine points before committing. The red flags are visible in advance if you know where to look.
Frequently Asked Questions
Why do most crypto projects fail after TGE?
Post-TGE failures almost always originate in decisions made before launch: inadequate vesting structures, no real liquidity strategy, absent marketing, regulatory non-compliance, or smart contracts that differ from disclosed vesting terms.
What is a token rug pull and how can investors spot one?
A rug pull occurs when project insiders exit their token positions rapidly, collapsing the price and leaving retail investors holding worthless tokens. Warning signs include short vesting cliffs with rapid unlock schedules and smart contract terms that differ from whitepaper disclosures.
What is VWAP-linked OTC in crypto and why is it risky?
A VWAP-linked OTC deal is a private token sale where the price is tied to the token's Volume-Weighted Average Price. It creates an incentive for the counterparty to manipulate trading volume and price to optimise their settlement terms.
Does moving to Dubai make a token launch regulatory compliant?
No. Jurisdiction of residence does not substitute for regulatory compliance in token issuance. VARA in Dubai has its own specific licensing and disclosure requirements. Projects with users in the EU, UK, or other regulated markets may face obligations under MiCA or FCA guidance regardless of where the issuer is incorporated.
How much liquidity does a token need at listing?
The liquidity budget must be determined by the token's expected trading volume, the number of listing venues, and the tokenomics. A market-making strategy should define minimum depth requirements for each trading pair and how the budget correlates with the vesting and emission schedule.