A 5-Step Framework for Designing Token Economics That Survive Regulators and Bear Markets
Regulators across MiCA, VARA, and CBB are now mandating token economic models before any licence is granted. Here's a rigorous framework for designing tokenomics that hold up under scrutiny — and under market pressure.

Ashish Homkar
Founder & CEO
- Published
- Reading time
- 7 min read
Tokenomics and token economic models are no longer just investor-facing documents. They're becoming regulatory requirements.
Under MiCA in Europe, VARA in Dubai, CBB in Bahrain, and frameworks emerging across APAC and MENA, Virtual Asset Service Providers and token issuers are expected to demonstrate economic coherence — not just narrative coherence — before receiving approval. Allocation spreadsheets are not enough. A regulatory-grade white paper requires demonstrating that the token model is structurally sound.
That means: design the economics before you launch. Before marketing. Before valuation discussions.
Here's the framework we use at Blockphrase when reviewing token models — five steps that take a project from concept to a model that can withstand both market pressure and regulatory scrutiny.
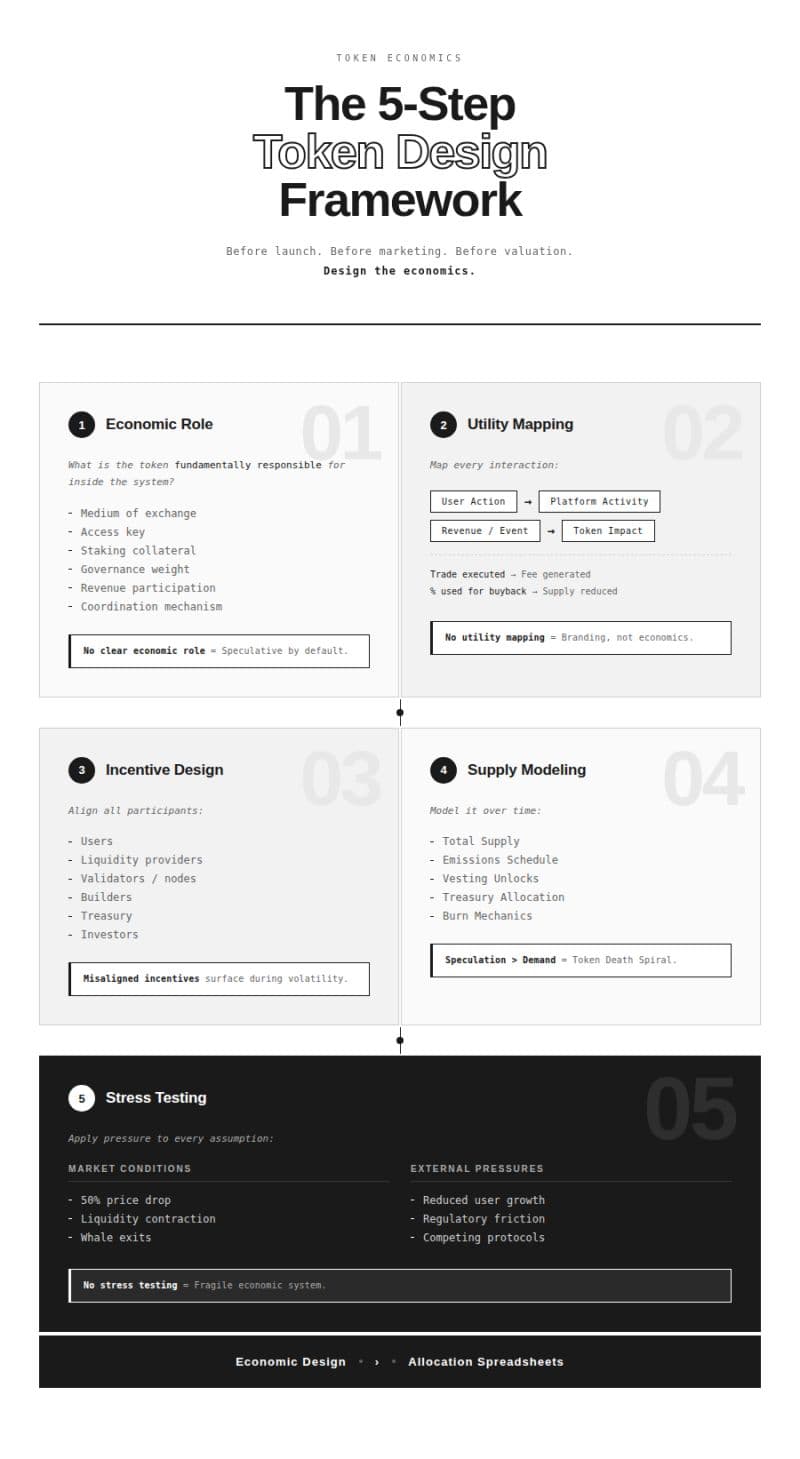
Step 1: Define the Economic Role
Start with a single, precise question:
What is this token fundamentally responsible for inside the system?
Choose one primary function:
- Medium of exchange — transactions are denominated in the token
- Access key — the token gates features, services, or participation
- Staking collateral — the token is locked to provide security or services
- Governance weight — token holdings map to voting power
- Revenue participation — token holders receive a share of protocol fees
- Coordination mechanism — the token aligns distributed participants toward a shared outcome
The reason this step matters: if you can't articulate the economic role in one sentence, the token doesn't have one. A token without a clearly defined economic function becomes speculative by default. Speculative tokens can perform in bull markets. They do not survive regulatory review or bear markets.
One function doesn't mean one utility. But there should be a primary economic role that everything else serves.
Step 2: Map Every Utility Pathway
Once the economic role is defined, map it. Draw the full pathway from user action to token impact.
A utility map looks like this:
User Action → Platform Activity → Revenue/Value Event → Token Impact
Example A (fee capture): Trade executed → Fee generated → % of fee used for buyback → Circulating supply reduced
Example B (service delivery): Node runs → Compute delivered → Rewards distributed → Circulating supply expands
Example C (access model): User pays subscription → Tokens burned → Supply reduced → Remaining holders benefit
If you cannot diagram how real activity affects the token, you don't have utility. You have a vibe. Vibes are fine for marketing. Your regulator won't accept them.
Every pathway in your model should close a loop. If you draw the diagram and find that tokens only flow out (emissions) with no clear flow back in (demand creation, burning, locking), the model has a structural leak.
Step 3: Align Incentives Across Every Participant Group
Tokenomics fails most often not in the math but in the incentive misalignment. Every participant group interacts with your token differently. Design for all of them.
The key groups to map:
| Participant | What They Want | What They Might Do That Harms the System |
|---|---|---|
| Users | Cheap access, good UX | Farm and leave |
| Liquidity Providers | Yield | Exit when emissions drop |
| Validators / Nodes | Consistent rewards | Centralise, extract |
| Builders | Ecosystem grants | Build and exit |
| Treasury | Long-term sustainability | Underspend on growth |
| Investors | Token appreciation | Dump at unlock |
For each group, ask: who earns, who pays, who benefits from long-term growth, and who can extract short-term value?
Misaligned incentives don't show up on launch day. They show up during a volatility event, a liquidity contraction, or a bear market — when every participant reverts to their individual rational interest. Design for that moment, not for the launch.
Step 4: Model the Supply Over Time
This is where most token models fall apart. Because supply modelling requires specificity that founders avoid.
Build a model that accounts for:
- Total supply — fixed or inflationary?
- Emissions schedule — when do rewards release, at what rate, to whom?
- Vesting unlocks — team, investors, advisors — when does each tranche unlock?
- Treasury allocation — how much is reserved, for how long, controlled by whom?
- Burn mechanics — what triggers burns, at what rate, is it discretionary or automated?
Once you have those five elements mapped, simulate:
- 10,000 users — early stage, can the model sustain itself?
- 50,000 users — growth stage, does emission rate keep pace with demand?
- Flat growth — what if user growth stalls for 12 months?
- Market downturn — what if token price drops 60% and trading volume halves?
Most tokens fail supply modelling because emission > demand. The schedule releases supply faster than organic demand can absorb it. The result is predictable: structural sell pressure that compounds until a crisis event forces a manual intervention.
Step 5: Stress Test the Model
A token model that only works under optimistic assumptions isn't a model. It's a wish.
Apply the following stress scenarios:
- 50% price drop — does protocol revenue still cover operations? Does treasury survive?
- Liquidity contraction — can users exit without cascading the price?
- Reduced user growth — at 30% of projected growth, is the model solvent?
- Regulatory friction — if a major jurisdiction restricts the token, what's the contingency?
- Whale exit — if the top 5 holders sell simultaneously, what happens to supply dynamics?
For each scenario, answer:
- Does the system survive?
- Does the treasury last 24–36 months?
- Do incentives still make sense for each participant group?
If any scenario causes the model to collapse, that scenario is a design failure — not a market risk. Fix it before launch.
Token Design Is Economic Engineering
Allocation spreadsheets are the last step, not the first. They're the output of a completed model — not a substitute for one.
The framework above is not creative writing. It's not narrative building. It's economic engineering: defining functions, mapping flows, testing failure modes, and iterating until the model is structurally sound.
This is why regulatory bodies are beginning to require it. MiCA white paper requirements, VARA's token classification framework, and emerging APAC standards all push in the same direction: demonstrate that the token has a coherent economic function before you ask the public to buy it.
If you're currently designing a token model and want it reviewed through this lens — not validated, reviewed — we're open to conversations with serious builders.
The model should survive before it launches. Not after.
Want research like this applied to your project?
Related serviceTokenomics Design & Modelling